Maximize Asset Protection

Cops Learn Retirement

You risk your life, don't risk your retirement!
Pensions pay the bills, investments leave a legacy.

Officer-Ty

My focus was on career and keeping people but now that I'm gettting closer to retirement, I really wish I paid more attention to learning not only what I have  but what i should consider doing as well.   I'm happy to help other officers learn how to help their families.

Are you feeling confused and just plainly said, “overwhelmed” trying to understand retirement.  It’s understandable, you trained to fight crime NOT understand finances, insurance and taxes.   If you answer no to these next questions. this is why.; 

1) Do I have a Financial Advisor to help guide my retirement asset growth 

2) Do I have an Insurance Agent to help protect me in Retirement  

3) Do I have a Tax Strategist, not a Tax Prepayer, a true tax strategist to help make sure I am most tax efficient in retirement

How did you find your financial team…from work?  referral from a colleague?  referral from a friend or family?    

Help me save on TAXES TODAY

Are you confident that you are saving all that you can on taxes today?

Retirement Tax

Help me save on TAXES in RETIREMENT

Do you understand how Social Security, your pension and all of your other assets come together to create taxable income in retirement?

Best for Family

What's best for my FAMILY

Do you utilize the Survirship benefit to protect your Spouse or what other options should you consider before pulling the trigger on retirement?

Health Insurance

Health Insurance in Retirement

Can you get Health Insurance once you leave the department?   Know your options so you’re prepared.  This is a very important part of retirement so are you comfortable with your understanding?

Our Commitment

With a deep commitment to education and specializing in helping Law Enforcement Professionals since 2001, our team is well-positioned to help navigate the complexities of your retirement transition.

Latest LEO Podcasts

Level-Funded vs. Self-Funded Health Plans | Employer Guide

Compare fully insured, level-funded, and self-funded health plans, including employer risk, claims funding, stop-loss coverage, cash flow, and plan data...
Law Enforcement Retirement: Health Insurance, Benefits, and Life After the Badge

Review the pension, health insurance, COBRA, 457(b), life insurance, taxes, beneficiaries, and employment decisions officers should consider before retirement...
Self-Funded vs. Level Funded Group Health Plans in Phoenix

Compare self-funded vs. level funded group health plans, stop-loss coverage, Arizona underwriting, potential refunds, and plan flexibility for employers...
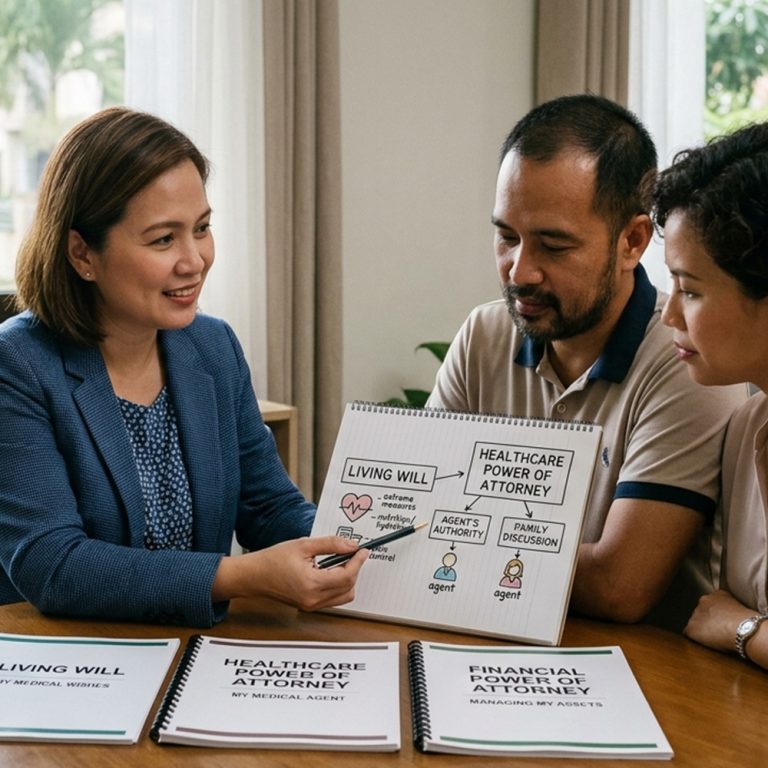
Living Will vs Healthcare Power of Attorney in Arizona

Learn the difference between a living will and healthcare power of attorney, how each document works, and why Arizona families may benefit from having both...
Will vs Trust: Estate Planning Basics for First Responders

Learn the difference between a will and a trust, why probate matters, why funding a trust is important, and why first responders and families should plan early...
Is Your Income Common Or Uncommon? Retirement Tax Questions Families Should Ask

Learn the retirement tax questions families should ask before retirement, including income taxes, qualified plans, Roth accounts, tax deferral, and long-term planning...

Be A Guest on our Podcast

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Pellentesque pellentesque efficitur orci, ut fermentum arcu facilisis id. Donec non auctor ipsum. Donec vestibulum enim et magna egestas varius. Morbi dictum ante ex, nec suscipit nunc maximus eget. Maecenas et lacinia sapien. 

The DROP Program

Perhaps the greatest strength of these plans is the ability for a police family to better increase their household liquidity at retirement. Invested prudently, assets can help mitigate the risk of long-term inflation while allowing tax deferral following your separation from police work, a period when many continue earning in a second career or job. Furthermore, DROP proceeds may be better structured to align with some of life’s most important goals and dreams, not just left to chance.

As DROP programs have increased in popularity, it’s been our experience that the administration of these plans typically varies by agency. Custodians typically maintain different rules and operational procedures, which can be challenging for participants and sometimes inflexible

Deferred Comp 457b and Thrift Savings Plan (TSP) investments and programs

These programs are popular for their convenience, ease of enrollment, and perceived low costs. However, most of these programs tend to have limited investment options and access to your money can be a challenge prior to the retirement separation. To our trained eye, they really provide value in managing income taxation at different points in your career. Our team can help you leverage them effectively.

Latest BLogs

Level-Funded vs. Self-Funded Health Plans | Employer Guide

Compare fully insured, level-funded, and self-funded health plans, including employer risk, claims funding, stop-loss coverage, cash flow, and plan data...

Law Enforcement Retirement: Health Insurance, Benefits, and Life After the Badge

Review the pension, health insurance, COBRA, 457(b), life insurance, taxes, beneficiaries, and employment decisions officers should consider before retirement...

Self-Funded vs. Level Funded Group Health Plans in Phoenix

Compare self-funded vs. level funded group health plans, stop-loss coverage, Arizona underwriting, potential refunds, and plan flexibility for employers...

Living Will vs Healthcare Power of Attorney in Arizona

Learn the difference between a living will and healthcare power of attorney, how each document works, and why Arizona families may benefit from having both...

Will vs Trust: Estate Planning Basics for First Responders

Learn the difference between a will and a trust, why probate matters, why funding a trust is important, and why first responders and families should plan early...

Is Your Income Common Or Uncommon? Retirement Tax Questions Families Should Ask

Learn the retirement tax questions families should ask before retirement, including income taxes, qualified plans, Roth accounts, tax deferral, and long-term planning...

Selecting Pension Payout and Survivor Benefit Options

If there’s one critical area, this is it, as elections for lifetime payouts are typically irrevocable. Historically, pensions had limitations with respect to survivor benefits and payouts for pensioners. We’ve seen many programs evolve over the last 2 decades, now providing flexibility to accommodate a myriad of options for survivors and beneficiaries. This presents a significant financial planning opportunity, as no two households are identical, and the historical one-size fits all approach to default pension benefits wasn’t ideal. 

Lump-Sum Pension Buyout (your contributions plus interest)

Exercising lump-sum pension payouts, whether full or partial, is also an area that can be fraught with pitfalls. It’s advisable to have a skilled professional guide you through the unique complexities of your agency’s plan to avoid costly mistakes and to weigh the pros and cons of different options before signing on the bottom line.

Our first priority is helping you take care of yourself and your family. We want to learn more about your personal situation, identify your dreams and goals, and understand your tolerance for risk. Long-term relationships that encourage open and honest communication have been the cornerstone of our success. 

Submit a Question for our Podcast to discuss